Before an asset owner decides how to dispose of an aging solar project, there is a prior question worth asking: does it need to come down at all? For a growing share of the US fleet, the more economically rational move is not to retire the site but to repower it by replacing the components that have aged while keeping the functioning equipment that still holds value.
Before 2030, even by most conservative estimates, more than 23 GW of US solar capacity is expected to need electrical upgrades. How owners handle that wave will shape portfolio returns for decades. Here's what repowering involves, when the economics favor it, and why the most valuable thing on an aging site is often not the panels at all.
What repowering actually means
Repowering is the replacement of aging equipment on an existing solar site with modern, higher-performing hardware while reusing the infrastructure that doesn't need replacing. No two repowering projects are the same, and the definitions vary by service provider, but at MaxFusion we distinguish two main types:
- Partial repowering. Swapping the components that have degraded or failed — most often modules, inverters, or aging cabling, while retaining the racking, foundations, and grid connection. This is the most common and most cost-effective form.
- Full repowering. A more extensive overhaul that may take a site down to its foundations, then rebuild with current-generation equipment. Closer to a new build, but still preserving the groundwork, permits, and interconnection.
Cost and disruption scale with how much you replace. Swapping modules or inverters is far cheaper than reworking the entire electrical balance of system, and the further down to the foundations you go, the closer the economics get to a greenfield build.
The value of repowering
The instinct is to see the panels as the value on a solar site. But in an aged project, they are typically worth the least. The most valuable thing on the site is usually the balance of system that has a longer lifecycle, and more recently - the grid interconnection. Interconnection timelines have lengthened sharply: the typical duration from connection request to commercial operation rose from under two years for projects built in 2000–2007 to more than four years for those built in 2018–2023, with projects in 2026 and beyond facing a median wait of more than five years.
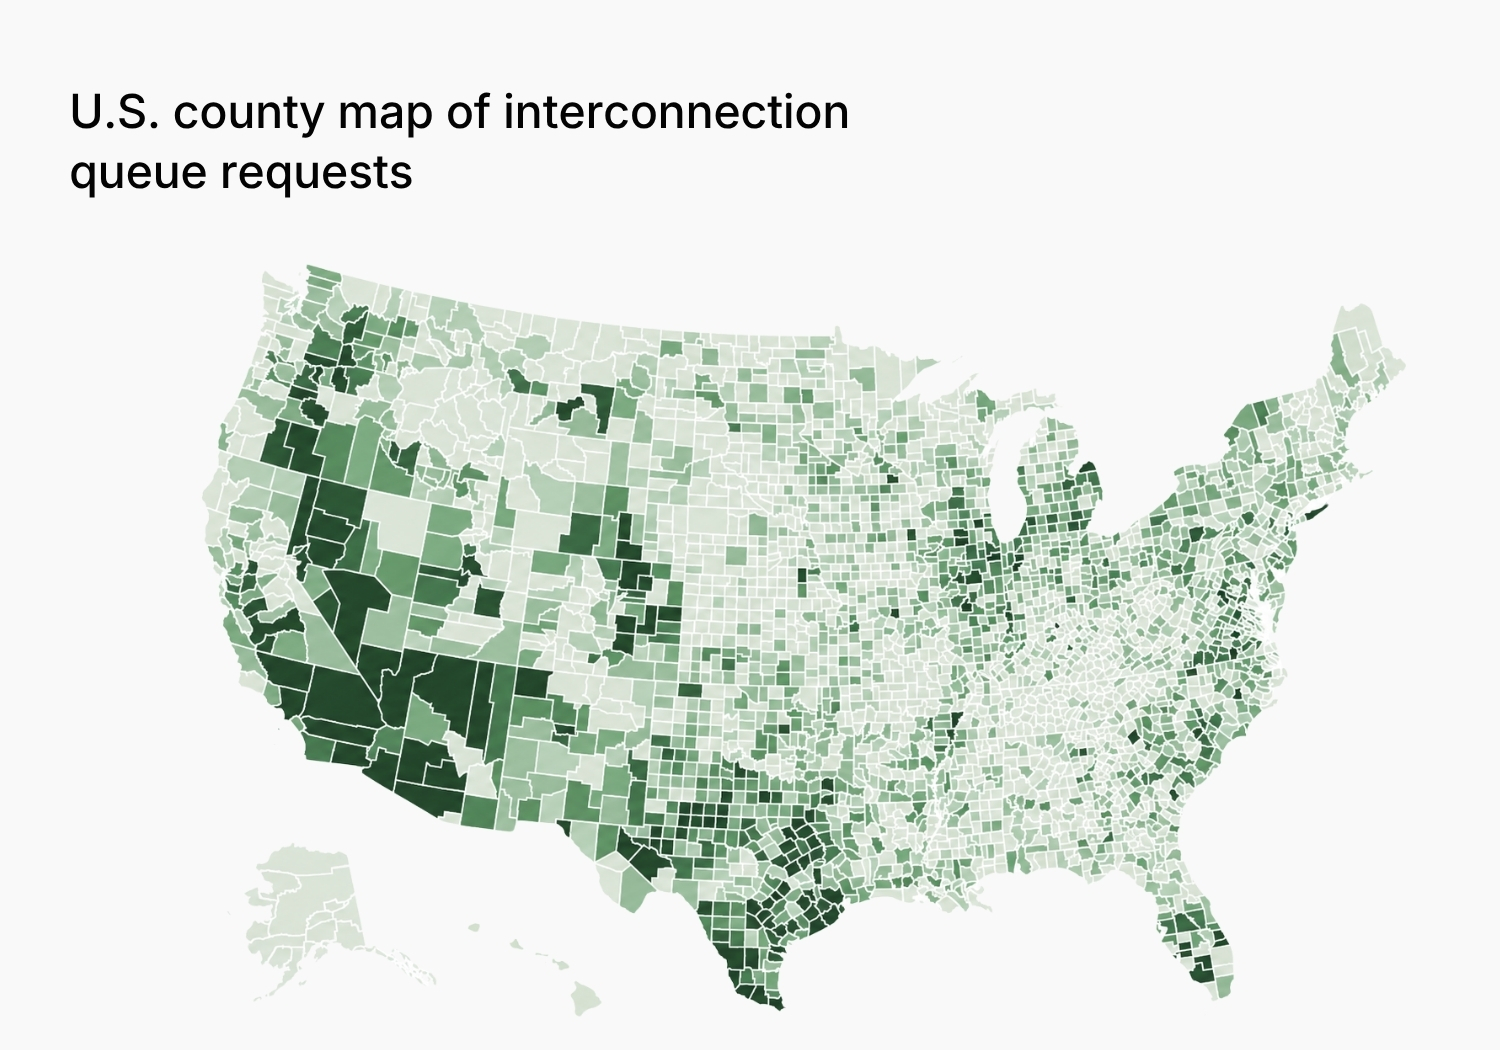
A live, energized interconnection point is therefore an asset that would take years to replicate on a new site. Repowering preserves it; decommissioning and rebuilding elsewhere would send the project to the back of a multi-year queue. All things considered, repowering can not only cost meaningfully less than a greenfield new build (with various industry estimates putting savings between 30 and 60 percent), but more importantly, provides an opportunity for continued power generation in a tightly bottlenecked market.
NOTE: a lot of the industry data is from the before OBBBA era; newly planned repowering projects should lean conservative.
An important limit: capacity, not just output
It is easy to overstate what repowering can add, so precision matters. Repowering can substantially lift a site's energy yield by replacing degraded modules with modern, higher-efficiency ones, recovering years of lost production. What it generally cannot do is freely expand the site's permitted export capacity.
Under federal rules, changes at an existing interconnection are assessed against whether they alter the originally approved interconnection service level. FERC's Order No. 2023 provides that adding or modifying facilities is not automatically treated as a 'material modification' so long as the change does not increase the requested interconnection service level. Exceed that level, and you typically trigger a fresh interconnection study — the very multi-year process repowering exists to avoid.
How much headroom exists before that threshold is not a single national figure; it depends on the specific grid operator's tariff and the gap between the site's original design and its approved service level. In our own project experience, a well-structured repower can often accommodate a modest uplift — on the order of 10–15% — within the existing envelope without a new study, though this varies by interconnection agreement and RTO/ISO rules. The gain from repowering, in other words, comes mainly from restoring and modernizing output within the permitted envelope, not from expanding the connection.
The mechanism that unlocks headroom and storage: Surplus Interconnection Service
There is a specific federal pathway worth knowing by name. Surplus Interconnection Service (SIS), established in FERC Order No. 845 and expanded under Order No. 2023, lets an owner use the unused portion of an existing interconnection — for example, the headroom between a solar plant's DC capacity and its approved AC interconnection limit — to add generation or storage without re-entering the full interconnection. Regional data shows how it is being used: grid operators report that the vast majority of surplus-interconnection requests involve adding storage to existing solar and wind sites. For a repower, SIS is the legal route that makes a storage retrofit a real game changer.
The economic crossover: when to repower
The core decision is a crossover calculation. Every year an aging array produces less through gradual degradation and, more sharply, through the failure of older modules and inverters. At some point the lost revenue from underperformance justifies the capital cost of replacing the hardware. Repowering makes financial sense when the value of the recovered and added output, over the remaining life of the site, exceeds the cost of the upgrade.
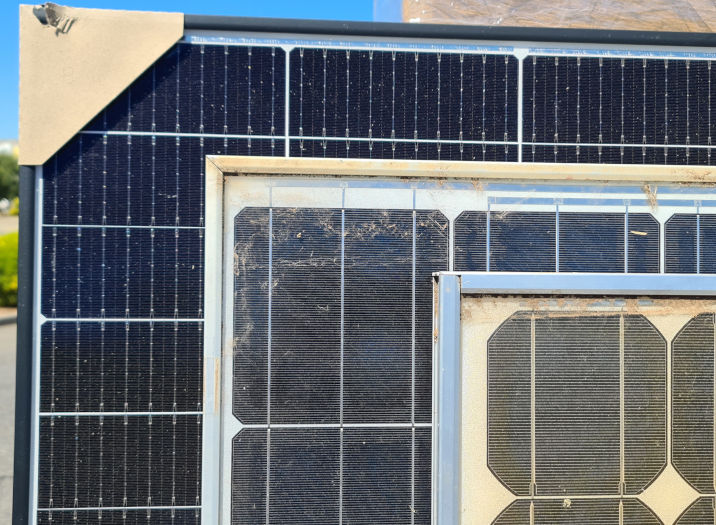
Two things push that crossover forward. First, the performance gap: modules from the early 2010s often ran at 15–16% efficiency, while current TOPCon modules reach 21–23%, so replacing them within the same footprint recovers a large share of lost yield. Second, timing: with new-build interconnection queues stretching for years, the output a repower restores comes online far sooner than the equivalent from a new project.
A note on tax credits: earlier repowering analyses leaned on the federal Investment Tax Credit and the IRS 80/20 rule to reset an asset's incentive eligibility. That lever has largely closed. Under the One Big Beautiful Bill Act, the commercial/utility 48E credit terminates for solar projects that did not begin construction by July 4, 2026 or are not placed in service by December 31, 2027. So for new repowering projects, solar ITC should generally be treated as unavailable — which means the economics increasingly need to stand on output and cost savings alone. Energy storage, however, retains the 30% ITC through 2033.
The new opportunity: adding storage during a repower
The most significant emerging trend in repowering is pairing the module upgrade with a battery energy storage (BESS) retrofit. A repower already mobilizes crews, opens the electrical system, and brings engineering to site, which makes it the natural, lowest-friction moment to add storage. Rather than a standalone storage project with its own mobilization and queue process, the battery is folded into work that is already happening, and where headroom exists, connected through the Surplus Interconnection Service pathway described above.
The mechanism is more elegant than simply "adding a battery." A repower with modern high-efficiency modules can place more generating capacity behind the same connection than the interconnection can export at peak. Ordinarily that surplus would be clipped and lost. A battery captures it instead — storing energy at the moments generation exceeds the export limit and releasing it later, when generation falls below it. At no point does the site exceed its approved interconnection level, yet it serves more energy across the day, and shifts it into higher-value evening hours. The interconnection cap limits instantaneous power, not total energy — and storage is how a repowered site extracts the difference.
The incentive picture reinforces this. While the solar ITC has wound down, standalone and co-located energy storage remains eligible. Adding storage during a repower can therefore capture an incentive the underlying solar upgrade no longer qualifies for, while turning a degraded, energy-only asset into a dispatchable one that can shift output to higher-value hours, firm its grid position, and open new revenue from capacity and ancillary markets. For many aging sites, the storage retrofit is the single highest value leverage available.
An illustrative feasibility model
The following is a modelled (isolated for a module-and-inverter repower) reference scenario: a 50 MW-AC, single-axis tracker plant commissioned in 2017 and repowered in 2027. It is illustrative only, intended to show the shape of the economics. A storage retrofit, financed through the surplus-interconnection and 30% ITC pathways described above, would be modelled separately for each site and sits on top of the figures shown here.
Every asset differs in condition, degradation, site works, offtake, and grid rules, so real feasibility must be assessed case by case — the figures below are a projection under one set of assumptions and should not be read as a guaranteed or typical outcome for any specific project.
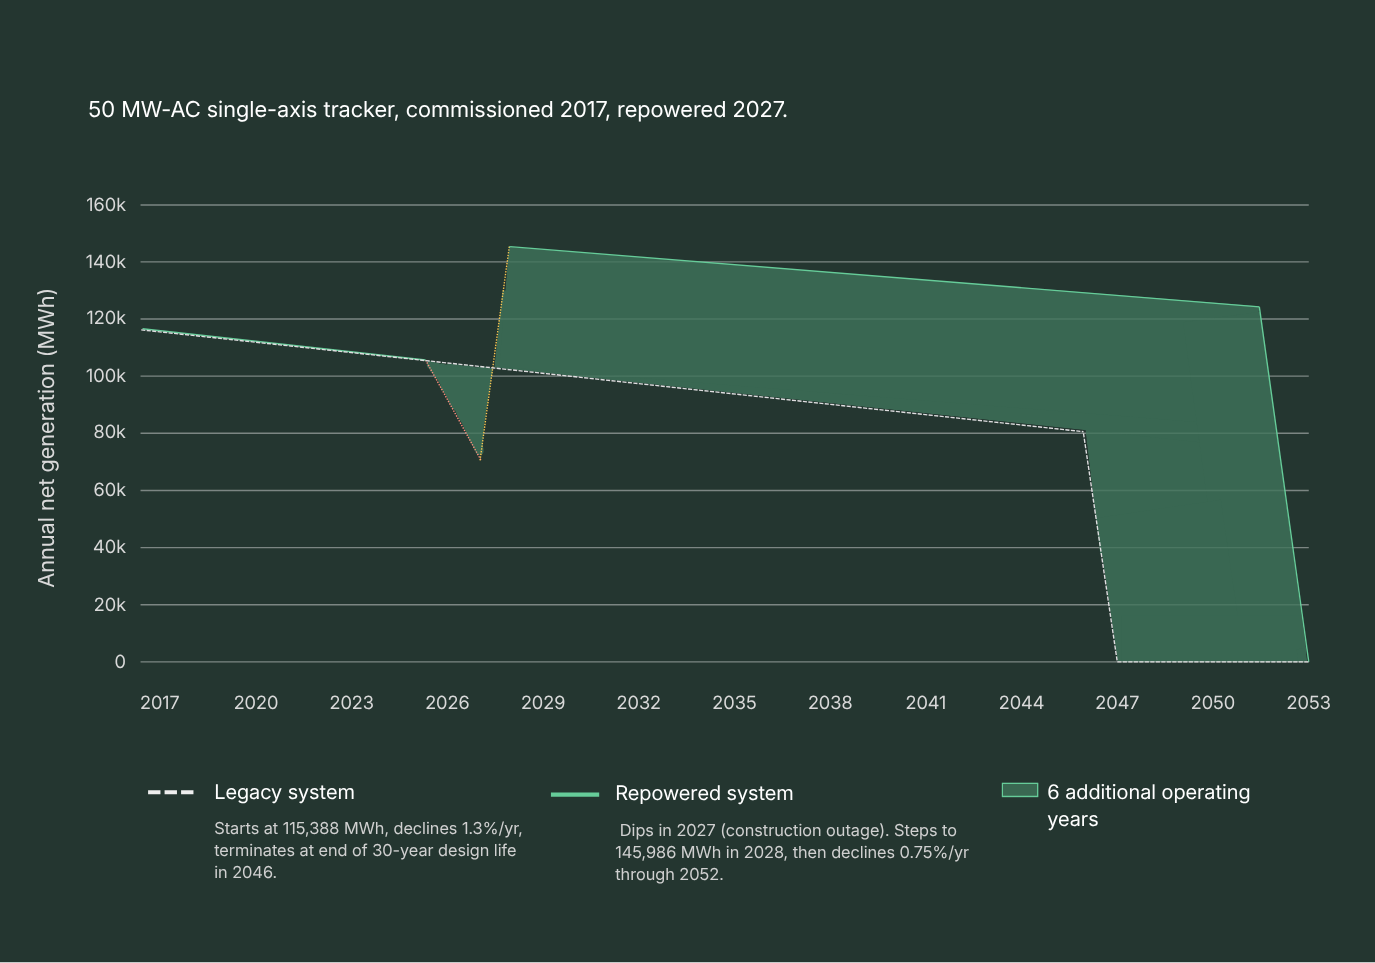
Modelled reference scenario only. The ~1.3%/yr legacy degradation reflects older-generation (pre-2015) modules plus inverter failures and soiling, and is higher than the ~0.5–0.75%/yr typical of modern installations. The ~25–30% saving is measured against full module replacement on the same site. Actual results depend on asset condition, site works, offtake terms, and local grid rules.
Read directionally, the model shows the shape of the argument rather than a promise: a one-year construction dip is traded for additional modelled operating years and materially higher annual output, at a capital cost below full module replacement, while keeping the 2017 interconnection intact. Whether any given asset lands near these figures depends entirely on its own condition and contracts — which is why a project-specific assessment, not a benchmark, is the only reliable basis for a decision.
Storage is where this picture changes most. Layering a BESS onto the same interconnection would alter the return profile materially — adding a dispatchable, ITC-eligible revenue stream on top of the restored output — but those figures are too site-specific to generalize responsibly, and belong in a project-level assessment rather than a reference model. The base case above is best read as the foundation that a storage retrofit builds on, not the full economic picture.
When repowering is the right call — and when it isn't
Repowering tends to win where:
- The interconnection is strong and hard to replace. A good grid position at a constrained node is the single biggest argument for reinvesting in the same site.
- The underlying infrastructure is sound. Racking, foundations, and site works that can carry modern modules without wholesale replacement.
- There is meaningful remaining offtake. A PPA or tariff arrangement worth extending output into.
- Storage can be added. Where a BESS retrofit can use surplus interconnection headroom, capture the 30% ITC, and unlock dispatchable revenue alongside the module upgrade.
It is the weaker choice where re-engineering costs run high. Replacing central inverters can trigger grounding and code upgrades, and significant work on a decade-old site may require it to meet the current electrical code (NEC 2026). Compatibility between old and new components, permitting complexity, and the loss of the solar ITC can all erode the case. Repowering is not automatically cheaper, but it is a better option when the reused infrastructure genuinely carries value and the upgrade scope stays disciplined.
What happens to the panels that come off
Repowering does not make end-of-life disappear — it defers and reshapes it. The modules removed during a repower still have to go somewhere. The same logic that governs any decommissioned panel applies: some may have residual resale or refurbishment value, but the bulk should move through a certified recycling route rather than to landfill, particularly as disposal regulation tightens.
This is where repowering and circularity connect. A well-planned repower pairs the upgrade with a compliant path for the retired modules — recovering silver, silicon, copper, and glass rather than landfilling them. For how those disposal routes compare, check our article.
The bottom line
For a large and growing share of the aging US fleet, the smartest end-of-life move is to extend the life of an operational site. Where the grid connection is valuable, the infrastructure is sound, and the upgrade scope is disciplined, repowering can lift output within the permitted envelope, extend asset life by years, and defer disposal costs — all while avoiding a multi-year interconnection queue. Increasingly, the addition of storage through surplus interconnection headroom is what tips the economics, capturing an incentive the solar upgrade itself no longer can. The owners who plan early, model their own numbers rather than a benchmark, and pair the work with a certified route for the panels that come off will be the ones who capture the value difference between one generation of solar and the next.